Represented by RISC-V, open Instruction Set Architectures (ISAs) boast advantages including open licensing, flexible scalability and low-cost customization, driving accelerated industrialization of hardware in recent years. A wide range of embedded MCUs, edge processors and AI accelerators have been launched, and global shipments of chips based on open architectures maintain rapid growth. Nevertheless, industrial prosperity is mainly reflected on the hardware side, while the development of the software ecosystem lags significantly, forming a core bottleneck restricting open ISAs from penetrating high-performance scenarios. Numerous engineering challenges remain unresolved across compiler toolchains, OS adaptation, application development kits and upper-layer software migration. In high-end areas such as servers and high-performance computing, challenges stemming from ecological barriers, performance optimization and compatibility are particularly prominent. This article sorts out the development gap between hardware and software for open ISAs, analyzes existing pain points within the software ecosystem, identifies maturity disparities across application tracks, and predicts long-term evolutionary paths and breakthrough directions for the ecosystem.
I. Rapid Hardware Industrialization: Sustained Robust Growth in Open ISA Chip Shipments
The core advantage of open ISAs lies in architectural openness. Manufacturers are exempt from hefty architecture licensing fees and can customize extended instructions according to scenario requirements to fit fragmented market demands. In the embedded IoT sector, numerous local semiconductor enterprises have launched general-purpose MCUs, wireless communication chips and sensor processing chips based on open ISAs, rapidly capturing the market for low-end 8-bit and 32-bit processors. Meanwhile, edge-oriented AI NPUs, real-time control processors and automotive auxiliary chips have achieved mass production, continuously enriching the hardware product portfolio.
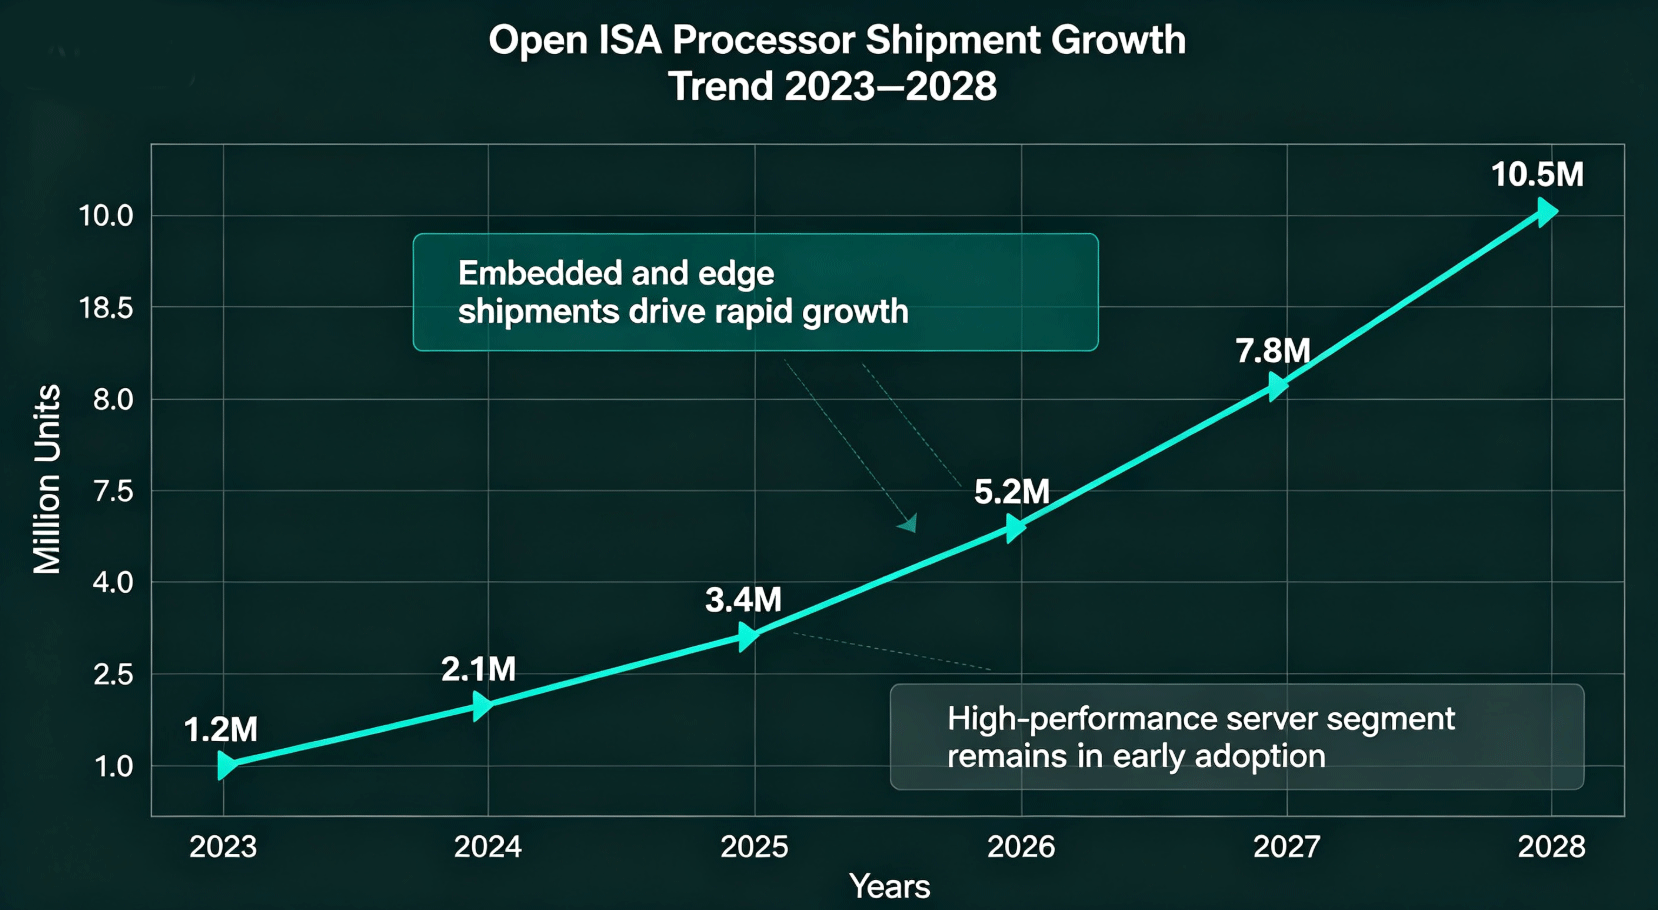
Across the globe, many semiconductor manufacturers and startups keep investing in core development. The variety of open-source core IPs continues to expand, ranging from ultra-low-power micro cores to multi-core out-of-order high-performance cores. Wafer fabrication partners continuously support tape-out verification, enabling mass shipment of chips built on mature process nodes. Market statistics show that shipments of open ISA chips have maintained rapid growth in recent years, and a stable commercial closed loop has taken shape in embedded scenarios.
The rapid expansion of hardware carries obvious characteristics: currently mass-volume products are mostly deployed in low-power, low-computing embedded scenarios with relatively low development thresholds. There are limited successful implementations of high-end processors for high-performance computing and general-purpose servers, and relevant hardware products are still in iterative verification. The pattern of hardware advancing far ahead of software has become increasingly evident.
II. Software Ecosystem Stands as the Greatest Industrial Bottleneck, with Multi-level Pain Points to Be Addressed
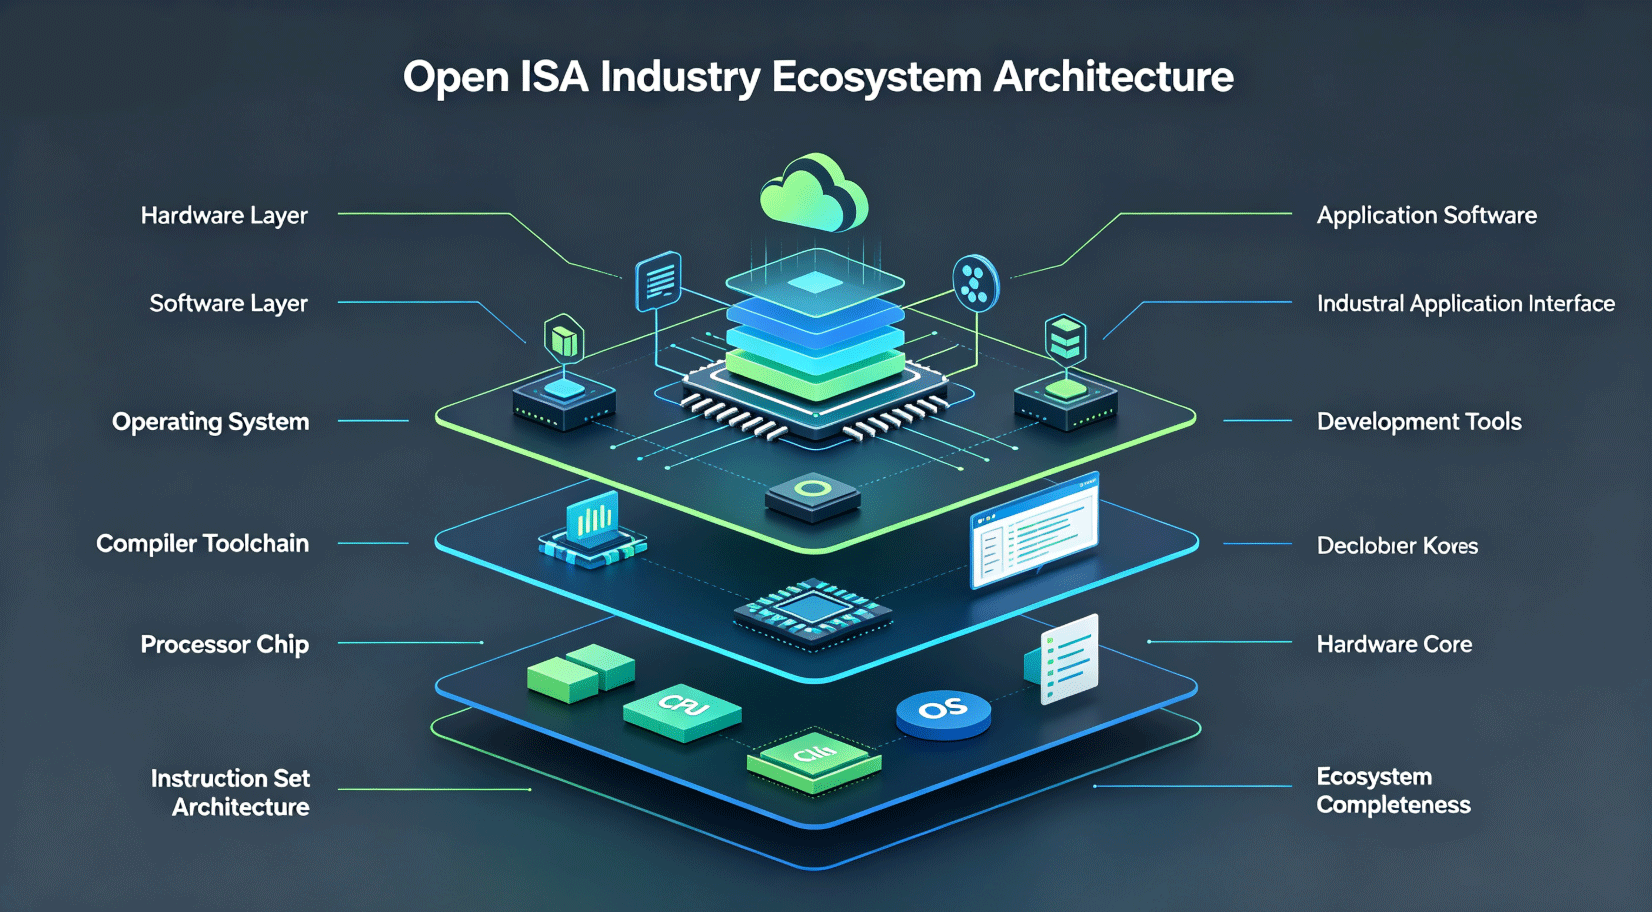
Compared with fast hardware deployment, building a software ecosystem requires a longer cycle and higher investment, making it the most prominent constraint for open ISAs. The software ecosystem covers multiple layers including toolchains, operating systems, drivers, basic libraries and industrial application software; deficiency in any link will hinder large-scale commercial adoption of chips.
First, compilers and fundamental toolchains lack sufficient maturity. Although GCC and LLVM keep improving support for open ISAs, customized extended instructions developed by different vendors lead to fragmentation. Optimization schemes for various cores and chips from different suppliers cannot be universally applied, increasing workload for software development and migration. Performance tuning tools, simulation and debugging tools offer limited usability, resulting in noticeably lower development efficiency than established architectures.
Second, operating system adaptation suffers fragmentation. Adaptation of embedded real-time operating systems is gradually improving, yet optimization of general Linux distributions for high-performance cores falls behind. Porting desktop and server operating systems demands massive workloads, with stability and scheduling efficiency requiring continuous refinement. In addition, adaptation of virtualization and container technologies progresses slowly, failing to underpin the implementation of cloud-native scenarios.
Third, migration costs for upper-layer software are substantial. A large body of existing industrial software, databases, multimedia frameworks and AI inference libraries are natively developed for closed ISAs. Porting them to open architectures requires extensive reconstruction and testing. The shortage of precompiled binary packages forces developers to compile source code independently, raising barriers for application deployment.
Finally, the industry faces a shortage of software talent. Most developers have long worked with mature architectures, and only a limited number of engineers master low-level optimization, system porting and performance tuning for open ISAs, further slowing ecosystem iteration. Imbalanced development between hardware and software directly leads to the phenomenon of “available chips lacking supporting software and difficult commercial rollout”.
III. Significant Scenario Differentiation; Daunting Challenges Remain in High-Performance Domains
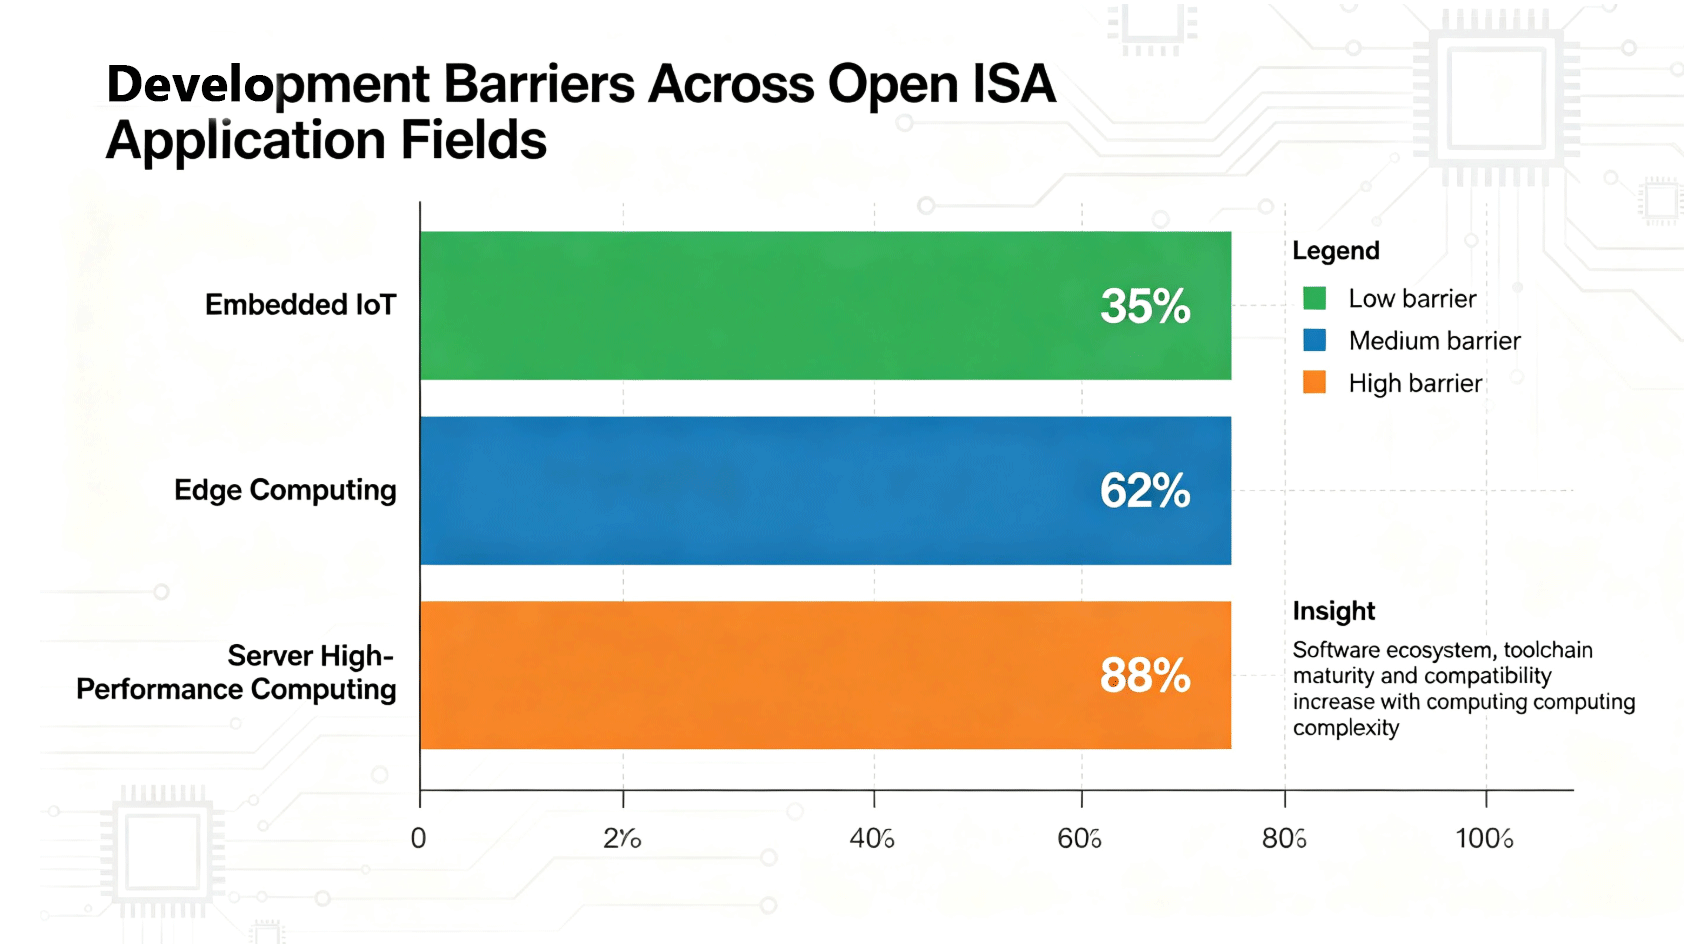
The maturity of open ISA ecosystems varies drastically across application tracks, accompanied by differing levels of challenges.
Embedded IoT scenarios have the lowest barriers with relatively simple requirements, where demands for real-time operating systems and lightweight applications can be readily met. This segment serves as the main battlefield where open ISAs achieve large-scale shipment. Leveraging low power consumption and low costs, relevant products have realized extensive commercialization.
Difficulty rises for edge computing and mid-tier automotive scenarios, which demand stable operating systems, complete drivers and functional safety support. These fields are currently in the gradual penetration phase and require continuous improvement of software toolchains and certification systems.
Server and high-performance computing domains encounter the most severe challenges. High-performance scenarios impose stringent requirements on memory consistency, multi-core scheduling, virtualization, I/O performance and ecological compatibility. Existing open high-performance cores still have room for improvement in single-thread performance and energy efficiency. More importantly, the server software stack is heavily dependent on mature closed-architecture ecosystems. Migration of databases, middleware, cloud platforms and virtualization software incurs exorbitant costs, reducing investment willingness among industrial chain participants. Industrial customers set strict standards for ecosystem completeness, long-term technical support and software stability, and show little willingness for large-scale replacement without mature software ecosystem backing.
In the short term, open ISAs will continue to take root in embedded and edge scenarios. The high-performance general-purpose computing track will remain a long-term strategic focus, and rapid substitution is unlikely.
IV. Accelerated Collaborative Ecosystem Development Amid Persistent Fragmentation Risks
Having recognized software deficiencies, stakeholders along the industrial chain have ramped up software investment. Foundations continuously promote standardization and unify specifications for extended instructions to mitigate hardware fragmentation. Chip vendors actively open adaptation tools, BSP drivers and software reference designs. OS suppliers and cloud service providers gradually launch system porting and optimization initiatives. Government-industry collaborative open-source projects keep emerging to advance co-development and sharing of fundamental software.
Nevertheless, ecosystem construction faces notable fragmentation risks. Numerous enterprises independently develop software adaptation solutions without unified standards, leading to incompatibility between hardware and software platforms from different manufacturers and raising overall ecosystem integration costs. Complete software stack development cannot be accomplished by a single firm alone. Ecosystem co-construction requires collaborative mechanisms across the industry to avoid redundant R&D.
A phased development strategy is sensible: consolidate the embedded market base and continuously capture low-power markets; steadily make breakthroughs in edge and automotive scenarios; and pursue progressive advances in high-performance fields without pursuing rapid short-term substitution.
V. Development Recommendations for Industrial Participants
Chip design enterprises should not only focus on hardware core R&D, but also invest in supporting BSPs, drivers and development tools to deliver integrated hardware and software reference solutions for customers and lower migration costs for terminal manufacturers. Active participation in standards organizations is critical to drive unified specifications for extended instructions.
Fundamental software firms should deepen engagement in key tracks, prioritize improving operating systems, AI inference frameworks and basic libraries for high-growth scenarios to build differentiated competitiveness, and conduct joint hardware-software optimization with chip vendors.
Terminal equipment manufacturers can pilot open ISA solutions in mature embedded and IoT scenarios, accumulate experience in software migration, and gradually expand toward higher-computing scenarios.
Investment institutions need to rationally distinguish opportunities across tracks. Embedded hardware delivers short-term commercial value, while high-performance processors represent long-term technological layout, requiring full evaluation of the software ecosystem implementation cycle.
Conclusion
The open ISA industry is at a special stage featuring rapid hardware expansion and ongoing software catch-up. Enriching hardware product portfolios and surging shipments prove the enormous industrial value of such architectures. However, deficiencies in the software ecosystem form a core obstacle to upward breakthroughs, with countless unresolved issues across toolchains, operating systems and upper-layer applications. Clear scenario differentiation exists: embedded tracks demonstrate viable commercial paths, while server and high-performance computing sectors face enduring high ecological barriers.
Ecosystem development requires sustained, large-scale cross-enterprise collaboration, and generally takes longer than hardware R&D. Whether the industry can overcome development bottlenecks hinges not on hardware chip performance, but on whether the entire industrial chain can jointly build a unified, mature and user-friendly software system. All participants should abandon fragmented development models, promote coordinated standards and joint hardware-software optimization, consolidate advantageous scenarios first, and then steadily extend into high-performance areas. With continuous improvement of the software ecosystem, open ISAs can fully unlock the benefits of architectural openness and deliver competitive end-to-end solutions across more computing tracks.

