The global semiconductor industry is transitioning from inventory correction to a structural recovery window. Analog chips and power semiconductors stand out as high‑elasticity segments in the current market cycle. Recently, multiple overseas and domestic chip vendors have initiated new‑round price revisions, signalling marginal shifts in supply‑demand dynamics. Booming downstream sectors including new‑energy power generation, energy storage, and electric vehicles as well as industrial automation have fueled rising demand for power management, signal‑chain, drive‑control and power devices. Meanwhile, growing emphasis on supply‑chain security and localization has opened a critical substitution window for domestic analog and power‑chip suppliers. This paper analyzes the underlying drivers behind the industry recovery and corresponding investment opportunities from four dimensions: price signals, demand structure, supply‑chain relocation, and competitiveness of local manufacturers.
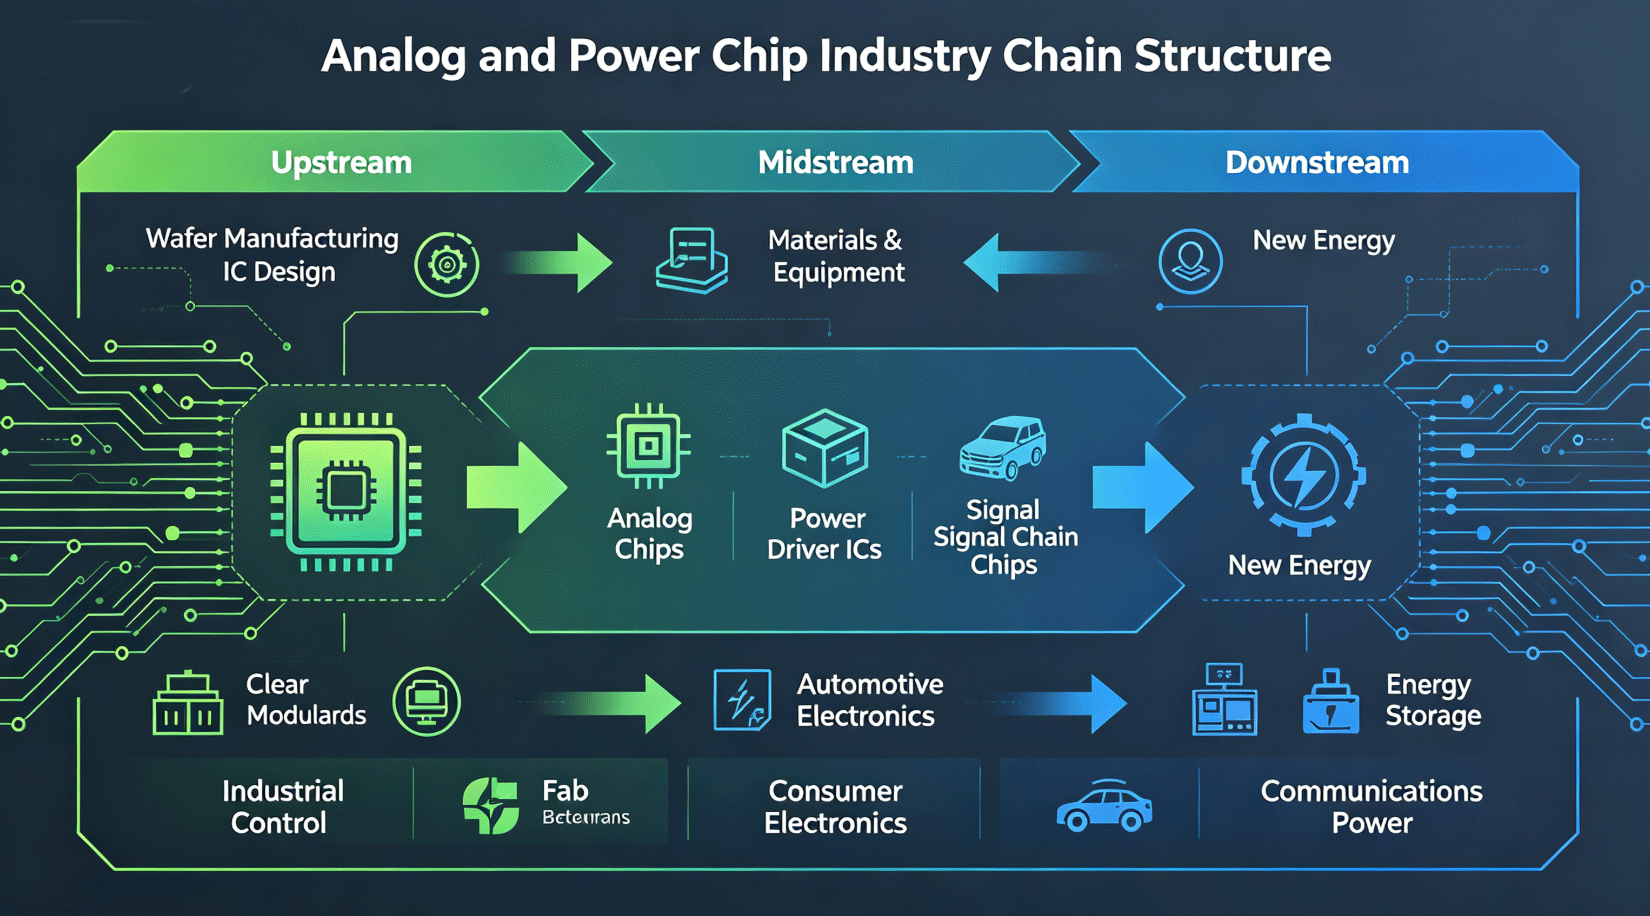
I. Price Adjustments by Multiple Firms Send Industry Signals; Improved Supply‑Demand Balance Drives Price Recovery
The concurrent price revisions by chip manufacturers are not merely short‑term promotions or cost pass‑throughs, but outcomes of inventory cycles and structural demand changes. After two‑year inventory destocking, analog chips and power devices suffered price pressure. Certain general‑purpose models faced fierce competition, channel inventories remained elevated, and fab utilization rates declined. Around 2025, downstream demand gradually rebounded with improving orders from new‑energy, industrial control and automotive electronics. Inventory levels across the value chain fell from highs, and supply‑demand balance was gradually restored.
Against this backdrop, price adjustments reflect recovering bargaining power across the industry. Analog and power‑chip products with high technical barriers, long customer‑qualification cycles and stable application scenarios demonstrate notable price elasticity. Compared with general‑purpose digital chips, analog chips feature longer product lifecycles and milder price swings. Nevertheless, price revisions serve as clear indicators of industry prosperity near inflection points.
Not all products see synchronized price increases during this round. High‑reliability automotive‑grade, industrial‑grade and new‑energy‑oriented products maintain robust pricing resilience, while consumer‑oriented analog chips still face intense competition with limited price recovery. Accordingly, industry opportunities show prominent structural divergence rather than across‑the‑board growth.
II. Rebounding Demand for Analog Chips; Power‑Management and Signal‑Chain Products Lead Recovery
Analog chips act as bridges between the physical world and digital systems, widely deployed in power management, signal amplification, data conversion, interface protection and drive‑control applications. Driven by intelligence, electrification and low‑power trends of end‑equipment, analog‑chip demand features rigidity and long‑tail characteristics. They are indispensable for battery management, charging control, display driving, sensor signal processing and industrial interfaces.
Power‑management chips are among the first segments benefiting from demand revival. Scenarios such as new‑energy vehicles, energy‑storage systems, photovoltaic inverters, data‑center power supplies and communication base‑station power supplies require large‑volume, high‑efficiency and stable power‑management solutions. Rising energy‑efficiency requirements fuel growing demand for high‑voltage, high‑current, low‑power and highly‑integrated power‑management ICs. Signal‑chain analog chips also gain momentum: industrial automation equipment, medical electronics, test‑and‑measurement instruments and smart sensors create strong demand for high‑precision amplification, analog‑to‑digital conversion and signal conditioning.
The analog‑chip sector is characterized by extensive product portfolios, diversified applications and solid customer stickiness. Mature analog chips can be reused across multiple industries and enjoy extended lifecycles once designed into customer systems, supporting relatively stable revenue for vendors. Still, manufacturers need comprehensive product portfolios and long‑term customer‑qualification capabilities.
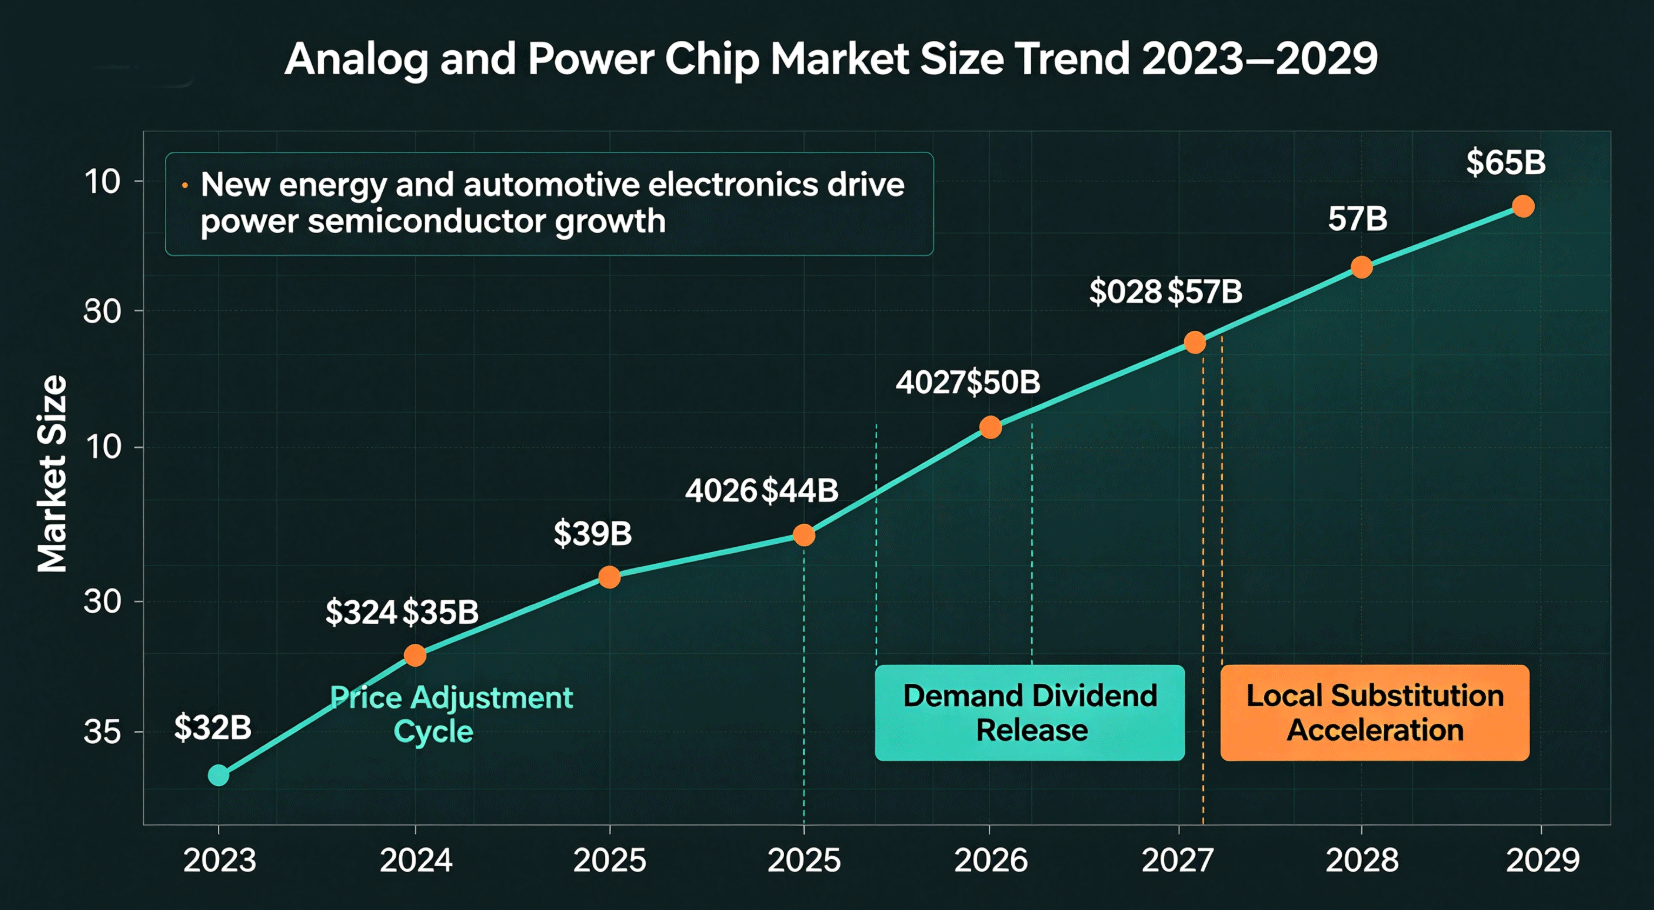
III. Power Semiconductors Benefit from Energy Transition; New‑Energy Vehicles and Energy Storage Serve as Core Growth Drivers
Power semiconductors are core components for electric‑energy conversion and control, directly determining system energy efficiency, stability and cost. Amid global energy transition, expanding sectors including photovoltaic power generation, wind power, energy storage, electric vehicles, charging piles and industrial motors sustain high‑growth demand for power semiconductors. Devices such as MOSFETs, IGBTs and SiC components play vital roles in high‑voltage, high‑frequency and high‑efficiency scenarios.
New‑energy vehicles represent one of the most powerful growth engines for power semiconductors. Powertrain systems, on‑board chargers, battery‑management systems, thermal‑management modules and high‑voltage safety systems require massive power devices. As NEV penetration rises, semiconductor content per vehicle keeps increasing, making power chips clear beneficiaries of the industrial chain. Energy‑storage systems also deliver substantial incremental demand: energy‑storage converters, battery‑cluster management systems and bidirectional charge‑discharge systems create strong appetite for high‑voltage power devices.
Industrial control continues to unlock new demand. Upgrades for industrial robots, servo motors, PLCs, frequency converters and UPS power supplies drive consumption of industrial‑grade power devices. Compared with consumer‑electronic applications, automotive and industrial scenarios impose stricter requirements for reliability, service life and temperature adaptability, accompanied by lengthy qualification cycles and high entry barriers. Vendors with automotive‑grade and industrial‑grade certifications hold stronger competitive advantages amid the current demand boom.
IV. Window for Domestic Substitution Opens; Local Manufacturers Seize Development Opportunities
Against global supply‑chain restructuring, semiconductor localization remains a long‑term theme. Featuring broad application coverage and large market space while long dominated by overseas players, analog and power chips constitute key tracks for domestic substitution. In recent years, domestic suppliers have achieved continuous breakthroughs in power management, signal‑chain ICs, MOSFETs, IGBTs and SiC devices, with improving product performance, completed customer qualifications and expanding market share.
Local manufacturers excel in rapid response, cost control, localized services, customized solutions and supply‑chain security. Compared with global incumbents, domestic enterprises stay closer to downstream markets and can quickly adapt to shifting customer requirements, showing strong adaptability in emerging tracks including new‑energy, industrial control and automotive electronics. For mid‑to‑high‑end analog and power chips, local vendors are evolving from “functional availability” toward “superior performance” and “stable long‑term supply”.
Nevertheless, domestic substitution still faces headwinds. Analog chips place high requirements on manufacturing processes, design expertise and physical‑device understanding. Power chips impose strict standards for materials, fabrication, packaging‑and‑testing and reliability validation. High‑end automotive‑grade and industrial‑grade products involve prolonged qualification cycles and cautious customer adoption. Local firms must sustain R&D investment, enhance product consistency and stability, and strengthen customer stickiness via platform‑oriented product portfolios.
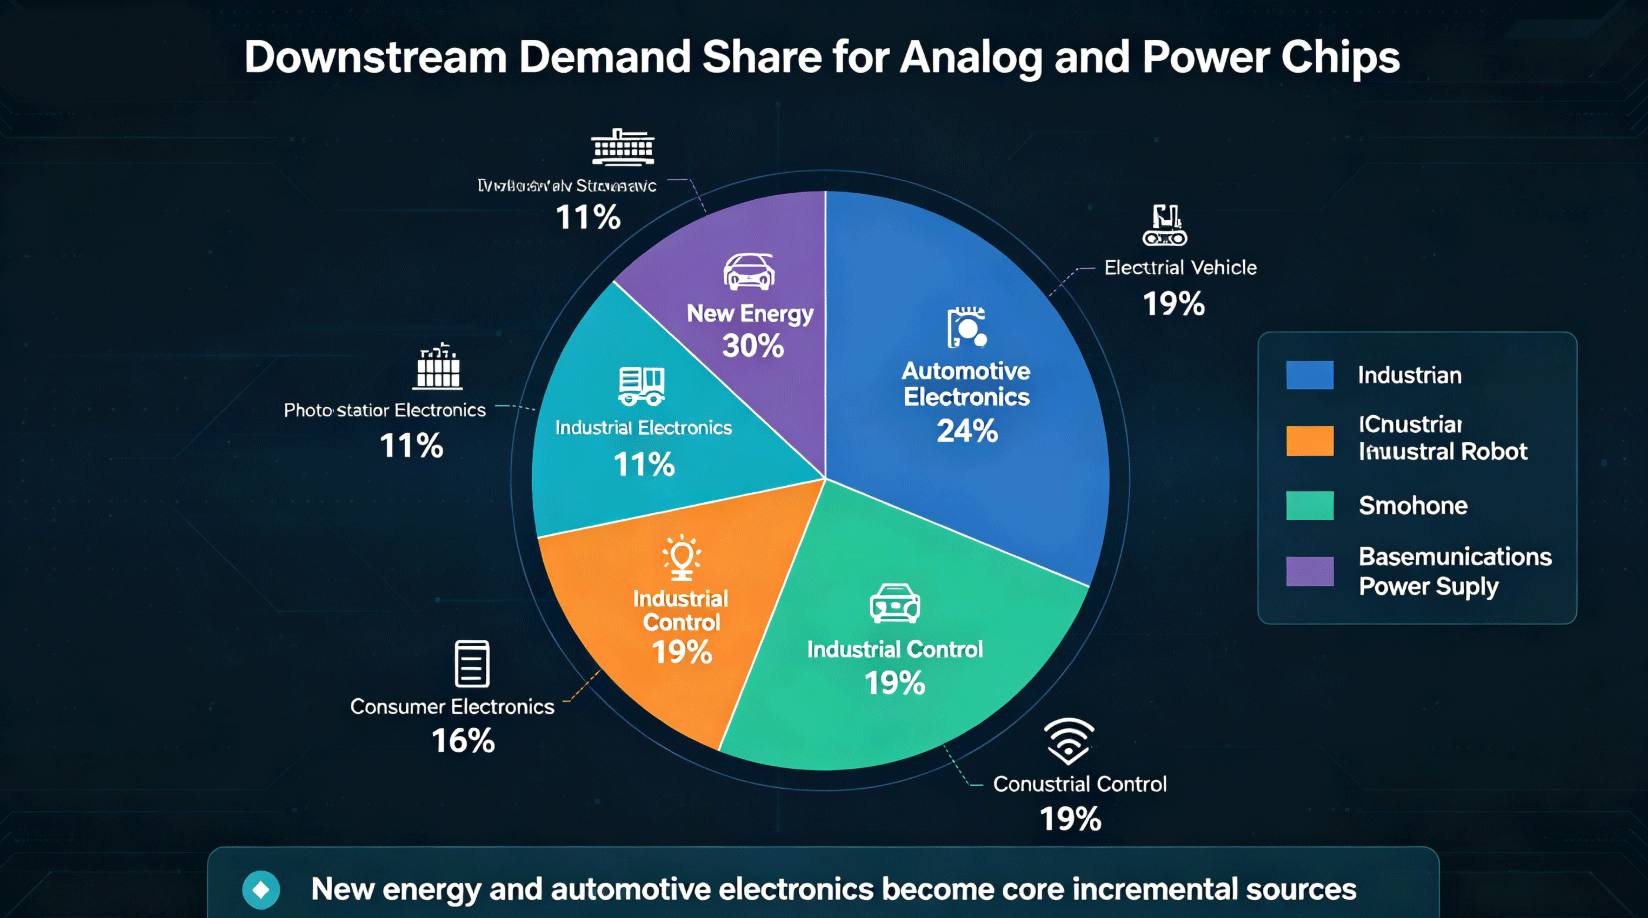
V. Industrial Development Suggestions and Investment Perspectives
For chip‑design enterprises, prioritize product layout around high‑boom applications such as new‑energy, automotive electronics, industrial control and communication power supplies. Power‑management ICs, signal‑chain chips, power devices and driver ICs feature solid demand resilience and merit long‑term deployment. Companies should avoid mindless pursuit of hot trends and attach importance to product certification, quality control and long‑term customer partnerships.
For manufacturing and packaging‑and‑testing enterprises, boost process capabilities for high‑voltage, high‑reliability and automotive‑grade products and deepen collaboration with design houses. Analog and power chips are heavily dependent on fabrication and packaging technologies. Advanced packaging, module packaging and system‑level packaging can lift product added‑value and competitiveness.
For downstream system manufacturers, gradually build diversified supply‑chain systems and expand adoption of local chips under preconditions of guaranteed performance and reliability. Joint validation, co‑defined product specifications and long‑run cooperation can improve supply‑chain stability and cost advantages.
For investors, distinguish cyclical recovery from structural growth. In the short run, price adjustments and inventory normalization bring industrial elasticity. In the long run, energy transition, vehicle electrification, industrial intelligence and domestic substitution jointly underpin growth logic. Focus on leading players with solid technical moats, customer qualifications, platform‑oriented capabilities and automotive‑grade product portfolios.
Conclusion
The analog and power‑chip industry sits at the confluence of three major trends: price recovery, demand expansion and domestic‑substitution momentum. Round‑of price adjustments by multiple manufacturers signal improving supply‑demand conditions. Downstream sectors including new‑energy, automotive electronics and industrial control deliver sustained demand dividends for analog chips and power devices. Benefiting from supply‑chain security requirements, localized services and strong adaptability to emerging markets, local suppliers face a critical substitution window.
Future competition is no longer limited to individual‑product rivalry, but comprehensive contests covering technology platforms, product portfolios, customer qualification, supply‑chain assurance and cost control. Driven by downstream electrification, intelligence and low‑power trends, analog and power chips maintain ample long‑term market potential. Industry participants should capture the current demand dividend, consolidate technical accumulation and customer partnerships, and achieve high‑quality growth beyond simple scale expansion amid structural recovery.

