After multiple rounds of cyclical fluctuations, the global memory chip industry is undergoing profound restructuring of its supply-demand balance. Sustained capacity cuts and inventory destocking have pushed memory prices upward from troughs, lifting the industry out of the downward cycle. Leading overseas memory manufacturers represented by Samsung, Micron and SK Hynix have adopted notable strategic shifts. Instead of relying solely on domestic fabs, they have relaunched plans for capacity deployment outside their home markets. Meanwhile, generative AI continues to gain traction. Computing servers and AI acceleration clusters generate explosive demand for high-bandwidth memory and high-capacity memory chips, breaking the cyclical pattern dominated by traditional consumer electronics and effectively extending the ongoing prosperity cycle of the memory industry. This article reviews the evolutionary logic of the current memory cycle, interprets new trends in capacity planning by overseas manufacturers, analyzes structural changes in demand driven by AI, and assesses medium- and long-term competitive dynamics and development opportunities across the sector.
I. Inventory Cleared at Cycle Bottom, Memory Market Enters Recovery Path
In past years, weak demand for consumer electronics kept the global memory chip market in a state of oversupply. Shipments of end devices fell short of expectations, inventories piled up across distribution channels and end customers, and memory prices trended downward. Major overseas memory manufacturers proactively reduced capital expenditure, slowed capacity expansion, lowered wafer utilization rates, and adjusted supply through production controls, pushing the industry into a deep adjustment phase.
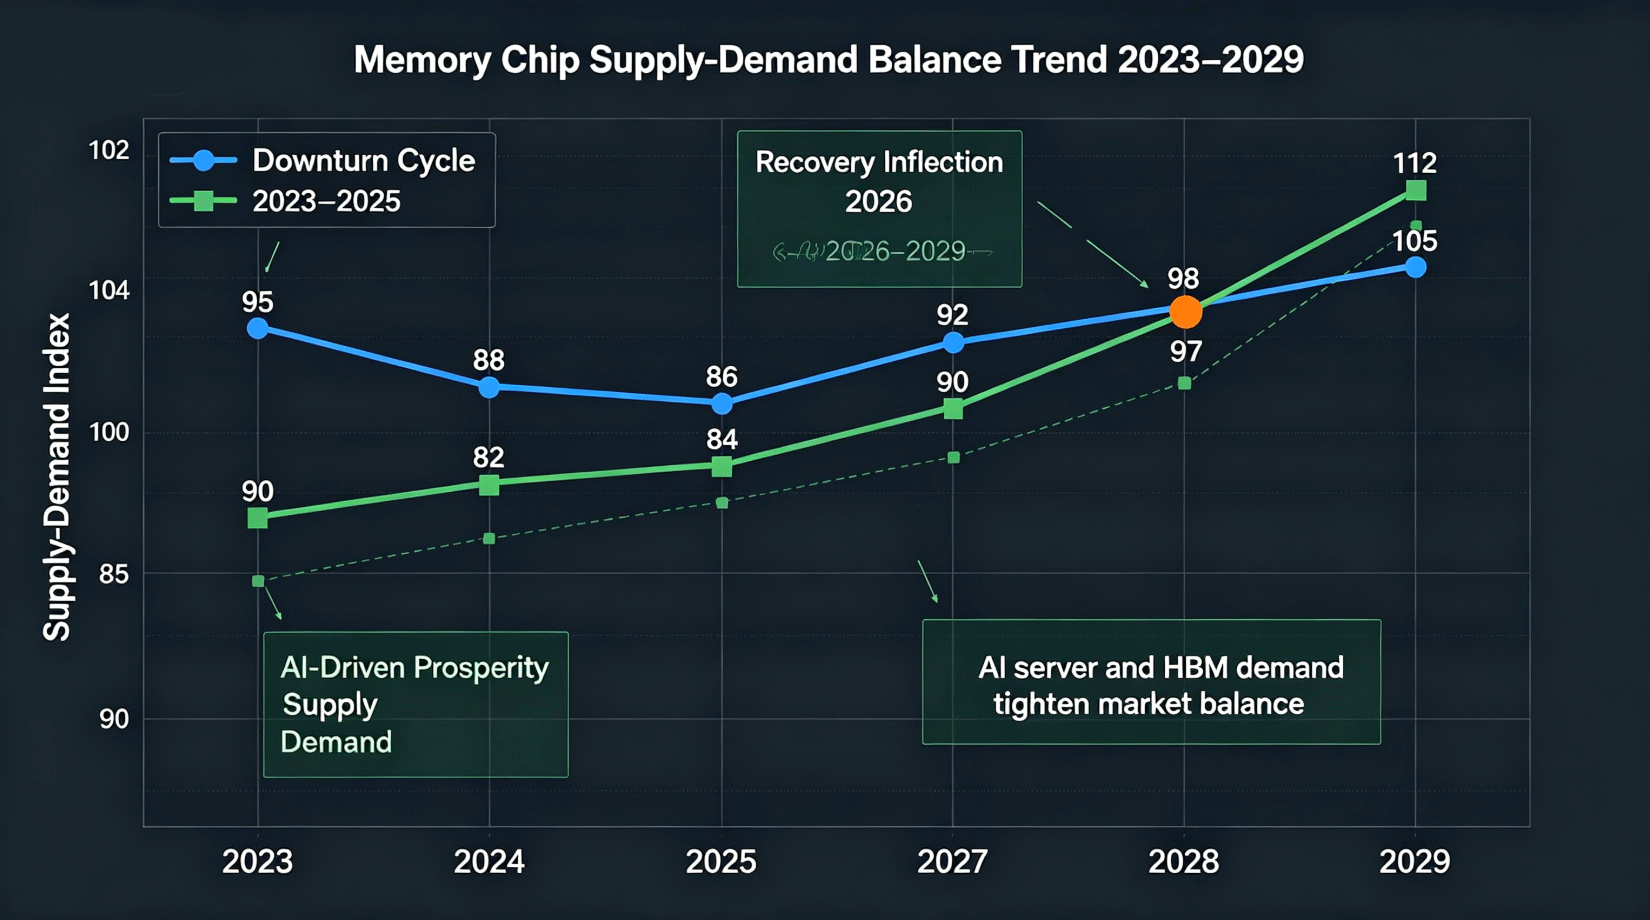
These sustained production cuts gradually yielded results. Inventory levels throughout the industrial chain declined from highs, easing supply-demand imbalance. Coupled with a recovering downstream server market, spot memory prices stabilized and rebounded first, followed by upward adjustments in contract prices, delivering marginal improvements to manufacturers’ profitability. Traditional memory cycles were mainly driven by consumer electronics such as smartphones and PCs, featuring rapid volatility and relatively short upward cycles. However, the rise of AI computing demand constitutes the biggest variable in this recovery, triggering fundamental shifts in market expectations.
A consensus has formed within the industry: a recovery solely driven by rebounding consumer electronics delivers limited sustainability. Incremental memory demand generated by AI will serve as the core driver sustaining high industry operating levels, making the current upward cycle markedly longer than the historical average.
II. Overseas Memory Giants Adjust Capacity Strategies and Accelerate Layout Outside Home Countries
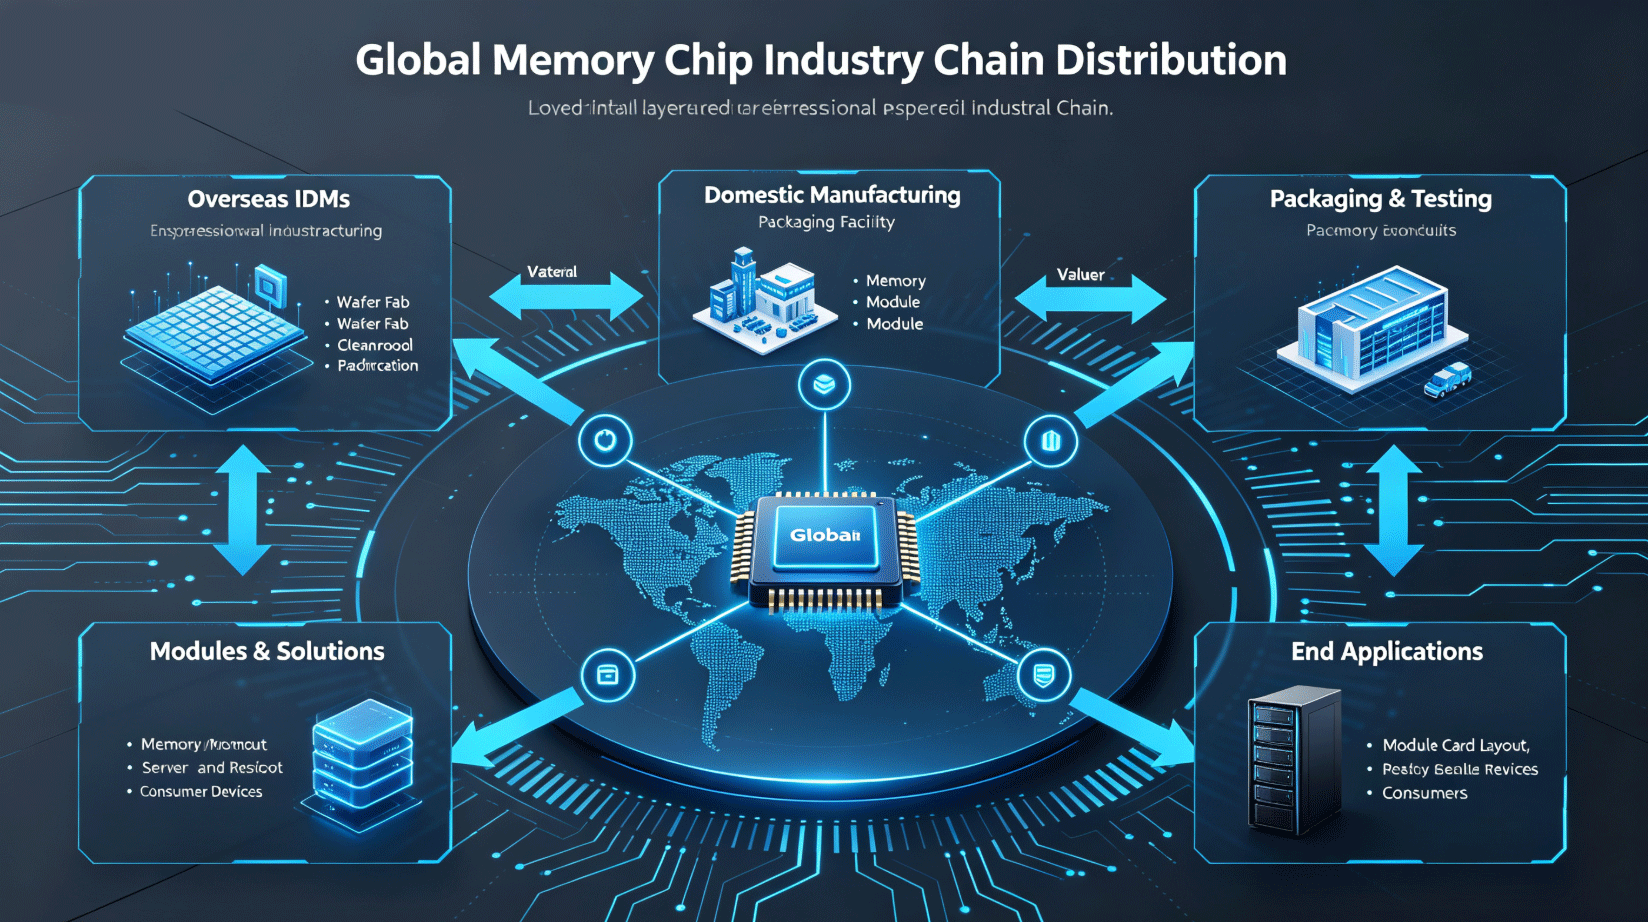
Amid the industry recovery, leading overseas memory enterprises have overhauled their capacity deployment approaches. For many years, Samsung, SK Hynix and Micron relied heavily on domestic wafer fabrication bases. Overseas facilities were mostly used for packaging, testing and supporting functions, with core wafer manufacturing capacity concentrated within their home territories.
Today, multiple factors prompt manufacturers to redesign their global capacity footprints. Shifting geopolitical conditions, pursuit of supply chain diversification, regional tariff and localization policies, and the need for risk dispersion are pushing major firms to move beyond purely domestic manufacturing models. Top players are re-evaluating the feasibility of overseas fab construction, exploring new or expanded wafer production lines outside their home markets or seeking strategic partnerships to diversify supply chain risks and get closer to end-market demand.
This shift in capacity strategy does not mean outward transfer of core technologies. Overseas giants maintain strict control over advanced processes, critical equipment and core R&D. Overseas capacity is mainly oriented toward mature process nodes and standardized memory products while enhancing delivery capabilities for regional markets. For domestic industries, expanded overseas memory capacity brings competitive pressure on one hand, yet opens room for collaborative opportunities in supporting links including packaging & testing, materials and equipment on the other.
The supply landscape is transforming accordingly. Global memory capacity will no longer be highly concentrated in a small number of regions, with supply sources becoming more diversified. The model where price swings are largely dictated by capacity fluctuations in a single region will gradually weaken. In the medium to long term, the magnitude of industry price volatility may moderate, while competition intensifies.
III. AI Reshapes Memory Demand Structure and Extends Industry Prosperity Cycle
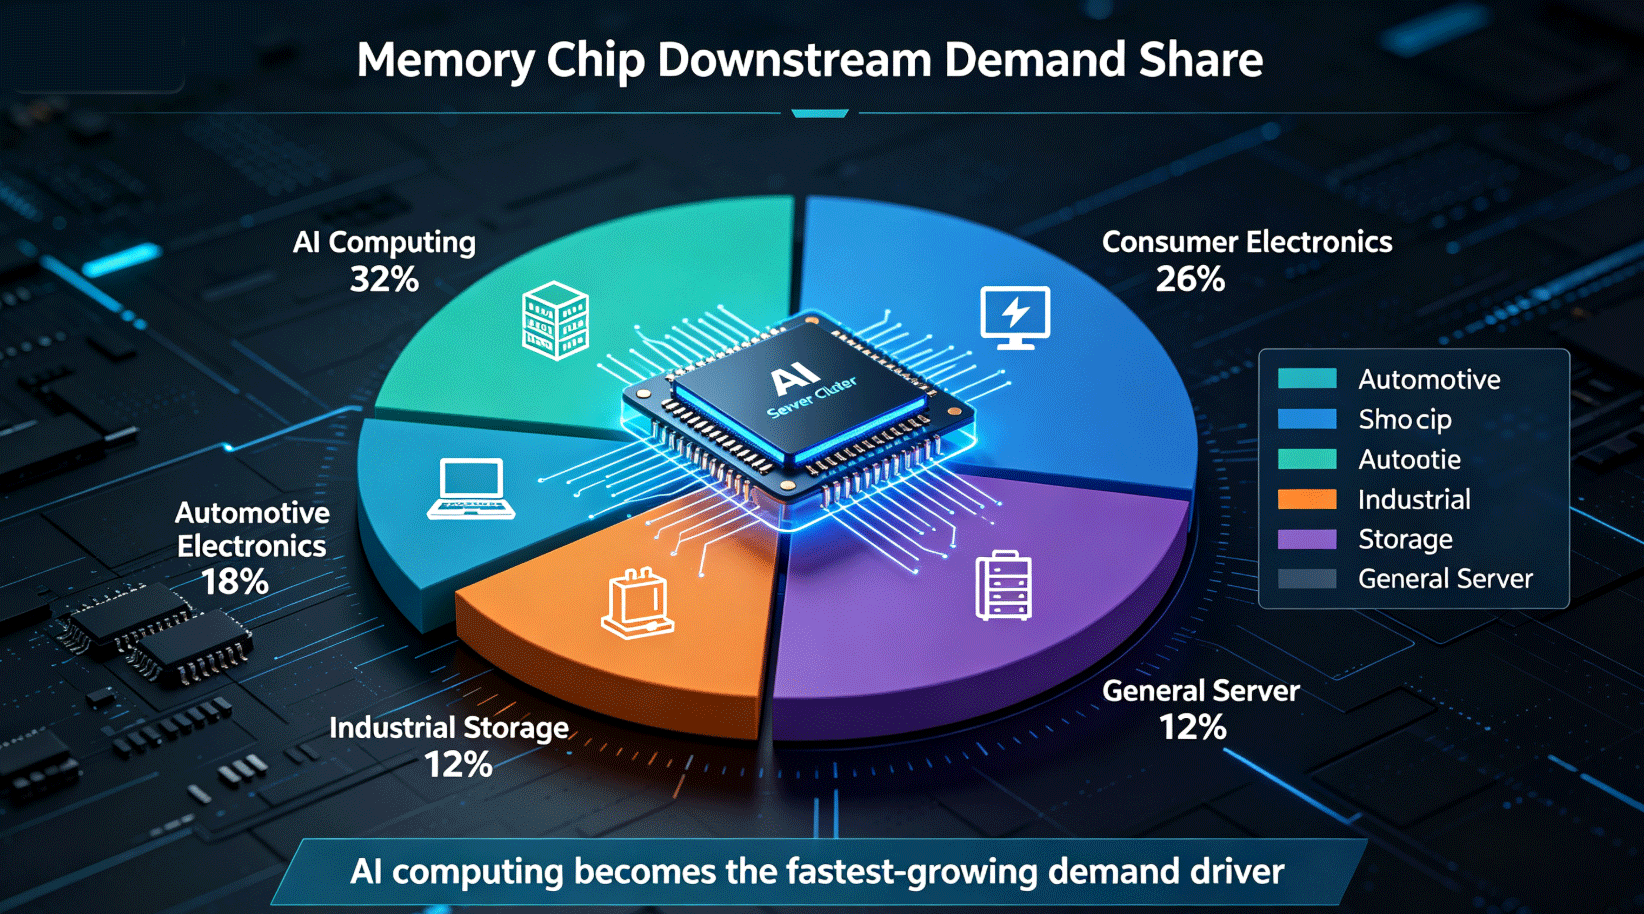
Traditional memory demand was led by general-purpose servers, smartphones and PCs, characterized by steady growth and strong cyclicality. The rise of the AI industry creates new requirements for memory within computing clusters. Large model training and inference servers demand high-capacity DDR memory, HBM, enterprise-grade SSDs and high-volume NAND Flash. A single AI server carries far greater memory capacity than a conventional general-purpose server, unlocking substantial incremental market space.
Unlike replacement-driven demand in consumer electronics, investment in AI computing infrastructure represents continuous new capital spending. Countries keep ramping up data center construction, and iterative AI models fuel sustained computing capacity expansion, driving rising demand for HBM, high-end DRAM and enterprise-grade NAND. As a core memory carrier for AI, HBM remains tight in supply and maintains significant product premiums, making it a key focus for overseas manufacturers.
Demand shows clear structural divergence: high-end AI-related memory products face shortages with strong price resilience, while demand for general-purpose memory chips targeting consumer electronics recovers moderately with limited upside for prices. The industry enters a structural bull market where high-end products benefit first and enterprise-grade memory gains rising value. Incremental AI demand offsets fluctuations in traditional end-market demand, mitigating downward cyclical pressures and lengthening the overall prosperity window.
IV. Industry Challenges and Outlook on Medium- and Long-Term Competitive Landscape
Significant uncertainties remain alongside opportunities. First, there is a time lag before overseas manufacturers’ expansion plans materialize. Concentrated release of new capacity in the coming years combined with slowing demand growth may trigger oversupply once again. Second, the development pace of the AI sector is subject to change. Investment scale in computing infrastructure is affected by industry profitability and capital conditions, so the sustainability of demand requires continued monitoring.
On the competitive front, overseas giants dominate high-end memory, HBM and enterprise-grade memory markets with advantages in technology, production capacity and customer channels. Domestic memory manufacturers keep advancing technological iteration, steadily lifting market share in general-purpose DRAM and NAND, focusing on consumer, industrial and automotive memory tracks, and gradually making inroads into the enterprise market. The global memory market forms a pattern where overseas players lead the high-end segment while mid-to-low-end segments face fierce competition.
The trend of globalized capacity layout will persist long-term, and supply chain diversification has become a shared choice for upstream and downstream participants. Reliance on supply chains concentrated in a single region is gradually abandoned, and regionalized, distributed capacity layout has become standard strategy for leading manufacturers.
V. Recommendations for Industry Participants
For memory chip design and manufacturing enterprises: seize structural opportunities brought by AI, increase R&D investment in high-end memory, HBM and enterprise-grade memory; rationally schedule capacity expansion to avoid homogeneous competition. Meanwhile, actively develop diversified supply chain partnerships to adapt to new trends in global capacity layout.
For downstream module and end-device manufacturers: establish multi-supplier systems to secure long-term supply, and optimize inventory management to cope with cyclical volatility.
For investment institutions: distinguish structural opportunities from broad market rallies. Prioritize high-end memory for AI computing and supporting memory materials and equipment sectors, and rationally assess cyclical risks in general-purpose memory.
Conclusion
The supply-demand landscape of the global memory chip industry is undergoing historic restructuring. Following sustained inventory destocking, the industry enters a recovery phase. Overseas memory giants have revised their prior capacity strategies and accelerated diversified capacity deployment outside home territories, reshaping the global supply map. Explosive demand for AI computing generates massive incremental memory requirements, breaking the traditional cycle dominated by consumer electronics and effectively extending the current industry prosperity cycle.
Future opportunities feature prominent structural characteristics. High-end AI memory products will continue to gain value, while general-purpose memory recovers moderately alongside traditional end markets. Industrial chain enterprises must acknowledge two major trends: capacity globalization and structural shifts in demand. They need to capture dividends from AI computing while guarding against cyclical risks stemming from future capacity release. Driven by adjustments on both supply and demand sides, the memory industry is moving beyond simple price boom-bust cycles into a new development stage defined by multi-dimensional competition over technology, production capacity and supply chain arrangement.

