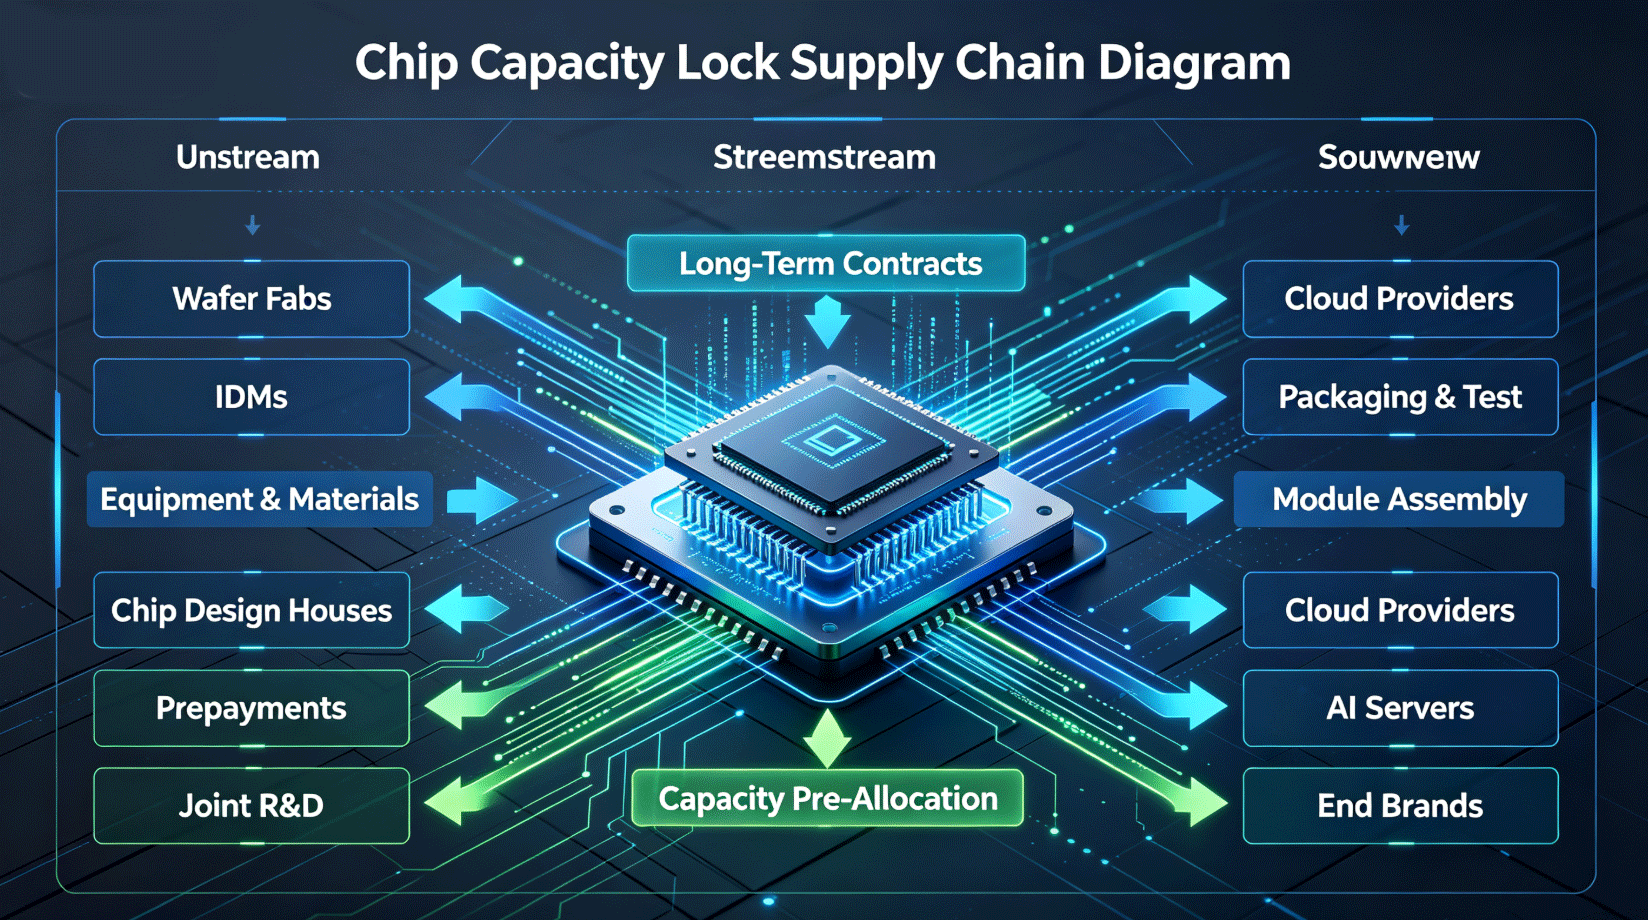
The global surge in computing‑power demand has sparked unprecedented capacity competition across the semiconductor industry. Driven by AI large‑models, cloud computing, autonomous driving and high‑performance computing, demand for advanced chips keeps climbing. Leading players secure future capacity via long‑term agreements, prepayments, joint R&D and pre‑allocation of production capacity. The conventional linear supply‑chain of “Design‑Fab‑Packaging & Test‑End Application” is being reshaped, ushering in a capacity‑lock era. Enterprises securing stable advanced‑process capacity in advance will gain upper hand in the computing‑power arms race. This article analyzes profound industry shifts from perspectives of computing‑power demand, capacity scarcity, long‑term‑contract mechanisms, prepayment models and rebalanced supply‑chain bargaining power.
I. Exploding Computing‑power Demand Renders Advanced Chips Strategic Assets
As AI models scale up rapidly, computing power has become core infrastructure for tech‑sector competition. Large‑model training, inference deployment, AI server clusters and high‑performance computing centers consume massive volumes of high‑end chips, including advanced‑process CPUs, GPUs, NPUs, FPGAs and high‑speed interface chips. For end‑device manufacturers, cloud service providers and AI enterprises, procurement of advanced chips goes beyond ordinary purchasing; it constitutes strategic investment linked to technical roadmaps, product iteration and market share.
In the past, chip procurement followed market price cycles: prices rose amid supply shortages and dropped when supply was ample. Amid the computing‑power arms race, advanced chips carry heightened strategic importance. Enterprises worry not merely about price hikes, but supply shortages. Delays in key‑chip delivery will hinder server roll‑out, large‑model training, product launches and business expansion. Accordingly, leading enterprises are shifting from spot purchasing to long‑term resource locking.
This transition reorients chip supply chains from cost‑driven principles toward supply‑security priorities. Price remains relevant, yet capacity availability, lead time, technical support and long‑term supply guarantees grow more critical. Advanced‑process chips are no longer simple electronic components; they have evolved into strategic resources for the computing‑power era.
II. Wafer‑Fab Capacity Scarcity Makes Advanced Processes a Fiercely Contested Focus
Chip‑manufacturing capacity expansion demands long cycles, massive capital outlay and high technical barriers, making rapid response to surging demand impossible. Constructing an advanced wafer fab — from planning and construction, equipment move‑in and commissioning to mass production — normally takes several years with enormous capital investment. Capacity expansion for high‑precision, high‑yield complex advanced processes poses even greater challenges.
Global advanced‑process capacity is highly concentrated among a handful of leading foundries. AI chips, high‑performance‑computing chips and premium smartphone chips rely heavily on advanced processes, turning corresponding wafer capacity into scarce resources. Chip‑design houses and end‑product brands must compete for limited advanced‑process capacity to safeguard competitiveness of next‑generation products.
Meanwhile, structural tightness emerges for mature‑node capacity. Power‑management chips, power semiconductors, memory chips, analog chips and automotive chips require stable manufacturing capacity, whose expansion is constrained by equipment, materials, talent and capital. Both advanced processes and specialty‑process capacity grow increasingly valuable.
Capacity scarcity reshapes industry bargaining logic. Whereas buyers previously adjusted short‑term orders flexibly, they must place bets ahead of time today; otherwise they risk falling behind product cycles.
III. Long‑term Contracts and Prepayments Become Core Capacity‑locking Tools
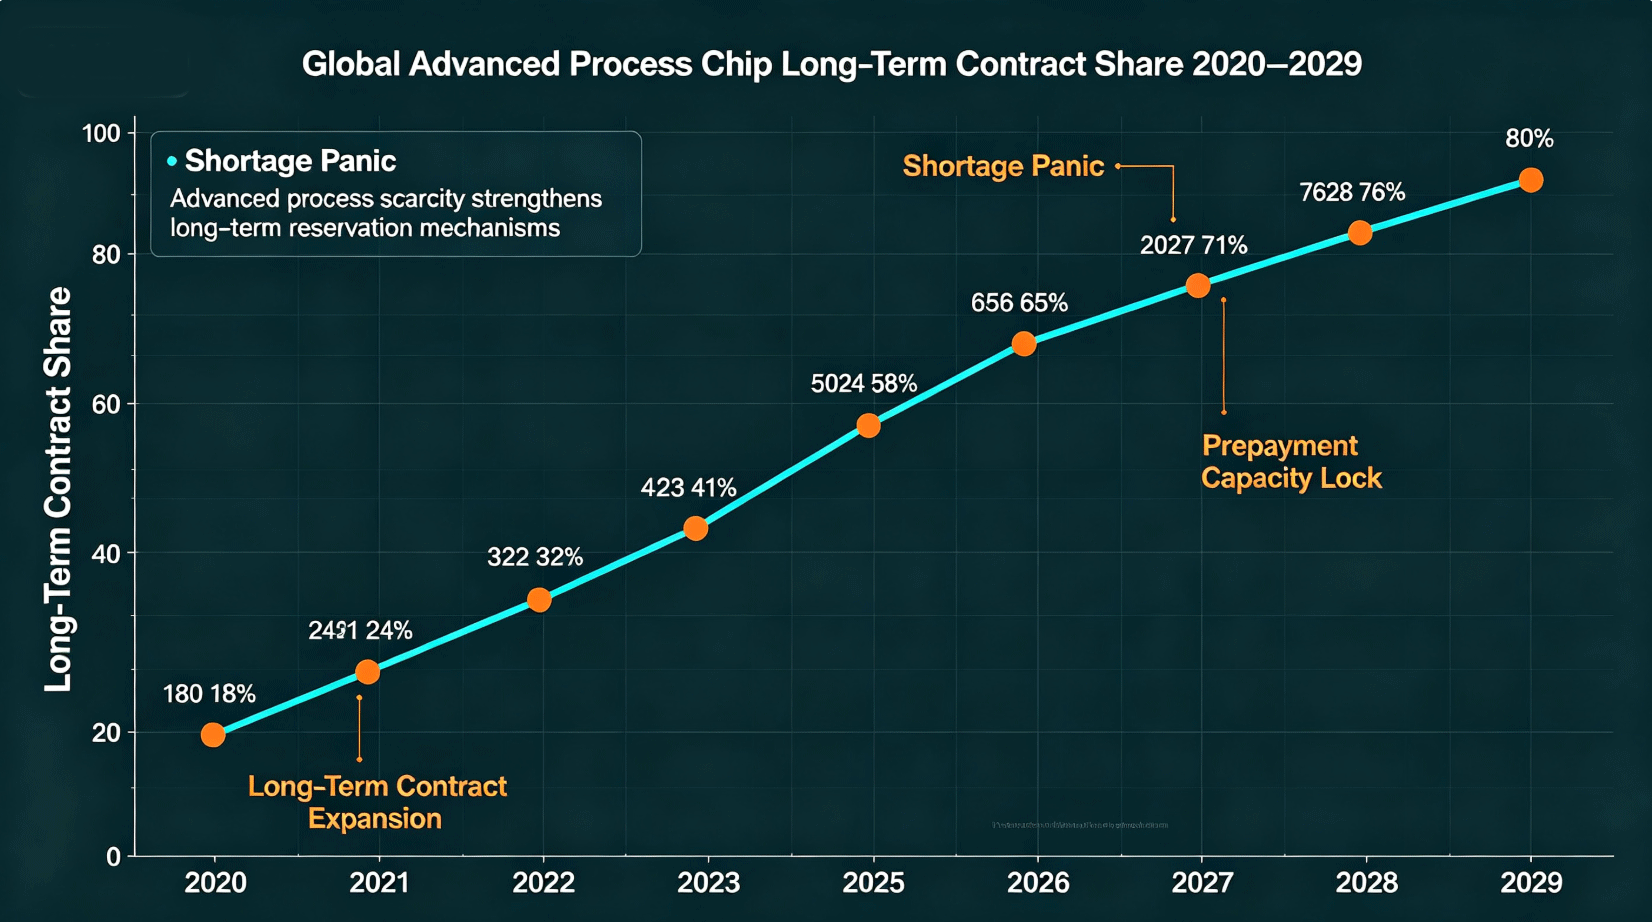
To mitigate capacity uncertainty, growing numbers of manufacturers adopt long‑term contracts and prepayment schemes to reserve future production capacity. Long‑term contracts stipulate procurement volumes, price bands, delivery schedules and capacity priority for coming periods. They help wafer fabs plan capacity in advance and lower risk of supply disruption for purchasers. Prepayments represent stronger commitment: buyers remit partial funds upfront in exchange for guaranteed capacity quotas and stable delivery.
Long‑term contracts and prepayments redistribute risks across supply‑chain participants. For wafer fabs, advance orders and capital reduce expansion risks and improve certainty for capital expenditure. For chip‑design houses and end‑product vendors, short‑term financial pressure rises, yet they gain priority access to scarce capacity and mitigate delivery volatility.
This model fits high‑boom, capital‑intensive, long‑cycle advanced‑process segments particularly well. AI‑chip developers, cloud vendors, server manufacturers and leading consumer‑electronics firms are financially capable of fulfilling prepayments and long‑term procurement obligations, and motivated to build competitive moats via resource reservation.
Nevertheless, capacity‑locking introduces new risks. Should downstream demand cool or technical routes shift, long‑term purchase commitments may translate into inventory burden and cost pressure. Enterprises must strike balance between supply assurance and excessive reservation.
IV. Supply‑chain Power Restructured: Wafer Manufacturers and Major Clients Gain Enhanced Bargaining Power
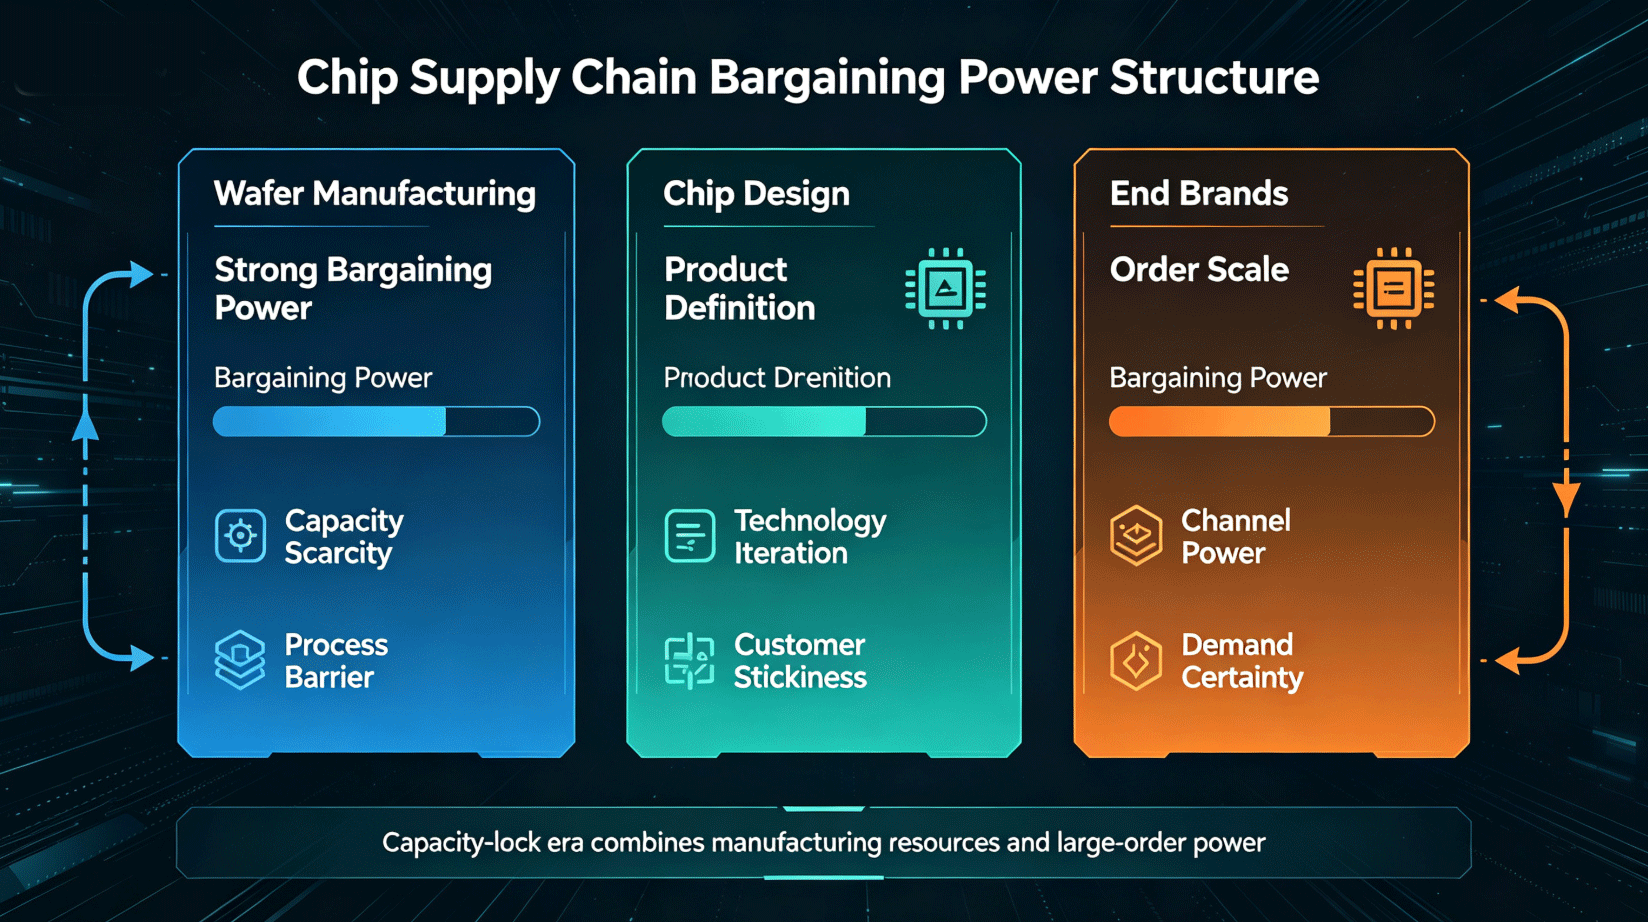
Capacity‑locking reshuffles bargaining power within chip supply chains. Under traditional frameworks, chip‑design firms and end‑product brands dominated product definition and distribution, while manufacturing played a service‑oriented role. Amid shortages of advanced‑process capacity, wafer foundries see markedly strengthened negotiating leverage. Foundries delivering stable advanced‑process technology and high‑yield capacity emerge as pivotal scarce links across the industrial chain.
Large‑scale financially‑strong clients also boost their influence. Cloud providers, AI enterprises, consumer‑electronics giants and automotive conglomerates secure higher‑priority capacity allocation through sizable long‑term contracts and prepayments. Small‑and‑medium‑sized manufacturers face greater headwinds: they can hardly afford heavy prepayments or obtain preferential capacity quotas.
Resources further concentrate toward top players. The future chip supply‑chain may follow this pattern: premium clients reserve advanced‑node capacity first, while smaller manufacturers compete for mature‑node and specialty‑process capacity. Small‑and‑medium‑sized design houses need flexible supply‑chain strategies including multi‑foundry cooperation, multi‑sourcing, optimized inventory management and reduced reliance on single processes.
V. Industrial Development Suggestions and Investment Perspectives
Chip‑design companies shall evaluate matching between product roadmaps and manufacturing resources in advance to avoid capacity shortages at critical stages. Establish stable long‑run partnerships with wafer foundries, reserving capacity quotas for advanced nodes, specialty processes and packaging‑and‑testing. Meanwhile, mitigate risks embedded in long‑term contracts and avoid over‑commitment to single application scenarios.
Wafer‑manufacturing enterprises shall deepen coordination with strategic clients to align capacity‑expansion timelines and improve build‑out efficiency. Leverage long‑term orders to de‑risk capital investment while retaining flexible capacity buffers for market volatility. Both advanced processes and specialty processes deserve prioritized deployment, especially for high‑demand fields such as AI, automotive electronics and industrial control.
Downstream end‑product manufacturers shall build multi‑supplier systems to mitigate risks from single‑source chip procurement. Secure long‑term supply guarantees for core chips while preserving cost‑effectiveness and flexibility for non‑critical components. Improve supply‑chain synergy through joint R&D, early‑stage engagement and co‑validation.
For investors, track themes covering advanced‑process capacity expansion, wafer‑fab capital expenditure, long‑term order volume, AI‑chip supply chains and domestic substitution. The capacity‑locking trend benefits firms with manufacturing moats, solid customer stickiness and leading‑edge technologies. Meanwhile, watch for cyclical swings, demand‑disappointment risks and potential capacity oversupply.
Conclusion
The computing‑power arms race pushes the semiconductor industry into a capacity‑locking era. Advanced chips become strategic assets, wafer‑fab capacity turns into scarce property, and long‑term contracts together with prepayments rewrite supply‑chain ground rules. Competition among chip enterprises extends beyond technology and product performance, encompassing capacity‑acquisition capability, supply‑chain negotiation competence and long‑term resource layout.
Enterprises securing advanced capacity earlier, more reliably and cost‑effectively will hold advantages in competitions for AI computing power, high‑performance computing, autonomous driving and next‑generation end products. At the same time, companies must guard against financial pressure, inventory burdens and demand shifts brought by long‑term commitments. In an era of heightened uncertainty, supply‑chain security, capacity planning and cost control jointly determine long‑term competitiveness for semiconductor firms.

